However, travelers should understand exactly what INF HOP provides before purchasing a plan. Travel insurance and visitor medical coverage can differ substantially from ordinary domestic health insurance, and benefits, exclusions, eligibility requirements, and limits depend on the specific plan.
This guide explains INF HOP insurance, its potential benefits, how coverage works, pre-existing-condition considerations, claims, eligibility, and the factors travelers should compare before choosing a plan.
What Is INF HOP Insurance?
INF HOP refers to travel-focused coverage and assistance options offered by INF for international travelers. The products are intended to help travelers manage unexpected medical and travel-related situations while outside their home country.
INF offers several types of visitor and travel insurance products, meaning HOP should not automatically be treated as identical to every other INF plan. Travelers should compare the actual benefit schedule and policy terms associated with the specific product they are considering.
This distinction is important because the level of medical protection, treatment for pre-existing conditions, emergency assistance, trip benefits, and other features can vary between plans.
Why Travel Insurance Matters
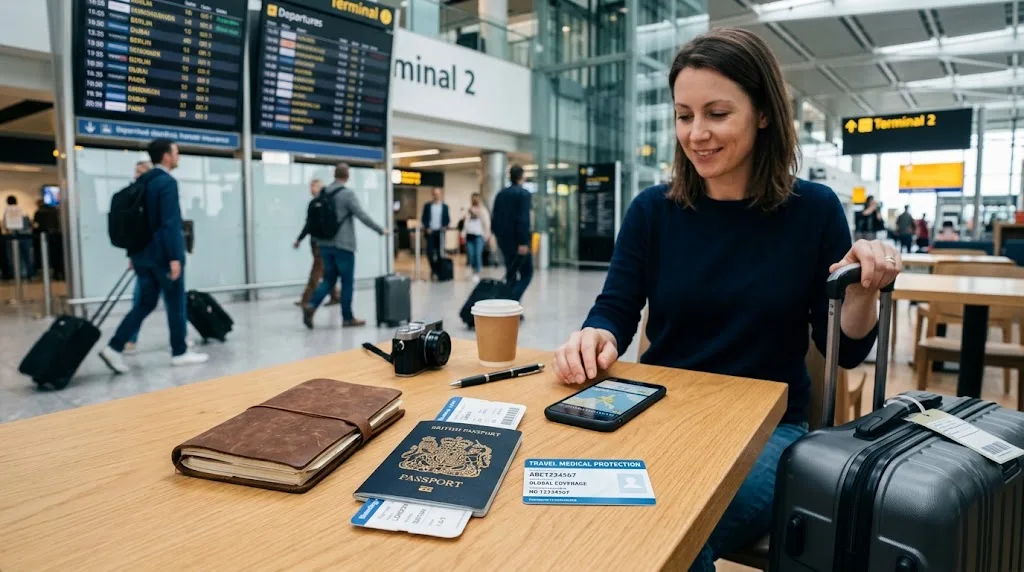
International travel can expose people to risks that are difficult to predict. An accident, unexpected illness, hospitalization, trip interruption, or travel delay can create significant expenses.
Medical care can be particularly expensive in destinations such as the United States. A suitable visitor medical insurance plan can help reduce the financial impact of eligible medical events while also providing access to assistance services.
Travelers should nevertheless remember that insurance is not designed to cover every possible event. The policy’s definitions, exclusions, limits, deductibles, waiting periods, and eligibility conditions determine whether a particular expense qualifies.
What Can INF HOP Cover?
The exact benefits depend on the INF HOP product selected, but travel-focused coverage can address several categories of risk.
- Unexpected sickness
- Accidental injuries
- Emergency medical treatment
- Hospital-related expenses
- Emergency medical evacuation
- Repatriation assistance
- Travel interruption
- Trip cancellation on applicable plans
- Baggage-related losses on applicable plans
- Assistance locating medical providers
- Emergency travel assistance
Not every benefit necessarily applies to every HOP option. Travelers should check the individual plan documents instead of assuming that a benefit mentioned in general INF marketing applies to every product.
INF HOP and Medical Coverage
Medical protection is one of the main reasons international travelers consider visitor insurance.
A travel medical plan can help with eligible expenses resulting from unexpected illness or injury. Depending on the plan, benefits can include physician visits, hospital care, emergency treatment, diagnostic services, and other covered medical expenses.
The amount of available protection matters because healthcare costs vary significantly by destination. Travelers visiting the United States should pay particular attention to medical maximums because even relatively straightforward hospital treatment can become expensive.
Does INF HOP Cover Pre-Existing Conditions?
Pre-existing conditions require especially careful attention when comparing travel insurance.
Some INF HOP options may provide coverage for an acute onset of a qualifying pre-existing condition. This should not be confused with unrestricted coverage for ongoing treatment of an existing medical condition.
An acute-onset provision generally focuses on a sudden and unexpected recurrence or worsening that meets the plan’s definition and eligibility requirements. The precise definition and limitations must be checked in the applicable policy or certificate.
Travelers with significant medical histories should therefore compare the pre-existing-condition provisions before purchasing a plan.
INF HOP Advantage
HOP Advantage is one of the travel-oriented options associated with INF. It is positioned as an option for international travelers seeking medical and travel-related protection without necessarily selecting one of the company’s broader visitor insurance products.
Depending on the selected option, benefits can include medical coverage, emergency evacuation, repatriation, and certain travel-related protections.
Travelers should compare the available medical maximums, deductible structure, pre-existing-condition provisions, exclusions, and travel benefits before choosing the appropriate level of protection.
INF HOP Prestige
HOP Prestige is another option designed for international travelers. It is positioned as a higher-level travel assistance option with broader benefit potential than some lower-cost alternatives.
Potential benefits can include medical expenses, emergency assistance, evacuation, repatriation, and qualifying assistance for certain pre-existing conditions.
The higher headline benefit level does not mean every expense is automatically covered. Travelers should still examine exclusions, eligibility requirements, benefit-specific limits, and claim procedures.
Who Is INF HOP For?
INF’s visitor insurance products are primarily designed for people who are traveling outside their home country.
Potential users may include:
- International visitors
- Tourists
- People visiting family abroad
- Parents traveling internationally
- Students and temporary visitors
- Travelers taking extended international trips
- Non-U.S. residents visiting the United States
Eligibility restrictions can vary according to the traveler’s residence, citizenship, destination, age, and selected product. Always confirm eligibility before purchasing.
INF HOP for Visitors to the United States
Visitors to the United States may have particular reasons to consider travel medical coverage. Healthcare costs in the country can be substantially higher than travelers expect, especially when emergency treatment or hospitalization is involved.
For this reason, visitors should look beyond the basic premium when comparing insurance. A lower-cost plan may have lower medical maximums or more restrictive benefits, while a higher-cost plan may offer broader protection.
It is also useful to understand how insurance claims work. Our existing guide on insurance claims and coverage provides additional context about documentation, coverage periods, and the claims process in a different insurance setting.
Emergency Medical Evacuation and Repatriation
Emergency evacuation can become important when appropriate medical treatment is not available at the traveler’s current location or when transportation to a suitable medical facility becomes medically necessary.
Repatriation can involve arranging transportation to the traveler’s home country under qualifying circumstances.
These services are often subject to specific medical and administrative requirements. Travelers should contact the designated assistance provider as soon as reasonably possible when an emergency occurs.
Does INF HOP Cover Trip Cancellation?
Travel benefits can vary considerably between products. Certain travel-oriented plans may include benefits related to trip cancellation, trip interruption, delayed travel, early return, or baggage problems.
However, these benefits generally apply only when the reason for the loss meets the policy’s definition of a covered event.
For example, simply deciding not to travel may not qualify for reimbursement. Travelers should review the covered reasons, documentation requirements, benefit limits, and exclusions before assuming a cancellation expense will be reimbursed.
How to File an INF HOP Claim
The claims process depends on the type of claim and the specific plan. Travelers should follow the instructions supplied with their insurance documentation and notify the appropriate assistance or claims service when required.
Useful documentation can include:
- Medical invoices
- Medical records
- Receipts
- Doctor or hospital reports
- Travel tickets
- Flight confirmations
- Cancellation documentation
- Police or incident reports where applicable
- Proof of payment
- Policy or membership information
Keep copies of everything submitted. Complete documentation can make it easier for the claims administrator to evaluate the request.
What Can Cause an Insurance Claim to Be Denied?
A claim can be denied or reduced when the event does not satisfy the applicable coverage requirements.
Potential issues can include:
- The event occurred outside the coverage period
- The treatment falls under an exclusion
- The condition does not meet the plan’s pre-existing-condition definition
- Required documentation was not supplied
- A benefit limit has been reached
- The expense is not medically necessary under the policy
- The traveler was not eligible for the selected product
- Required notification procedures were not followed
Travelers should read the certificate and benefit schedule before traveling rather than waiting until a claim occurs to discover important restrictions.
How Much Does INF HOP Cost?
The cost of travel insurance depends on multiple factors. These can include age, destination, trip length, selected benefit level, deductible, and the specific product purchased.
Because premiums can change and different travelers receive different quotes, there is no single price that accurately represents every INF HOP policy.
Instead of choosing solely on price, compare the total value of the coverage. A cheaper policy may provide substantially lower medical benefits or more restrictive conditions.
INF HOP vs. Traditional Health Insurance
Travel insurance should not automatically be treated as a replacement for ordinary domestic health insurance.
Traditional health insurance is generally structured around ongoing healthcare needs within a defined healthcare system. Travel insurance is designed primarily around unexpected events occurring during a trip and may contain specific limitations related to pre-existing conditions, routine care, geographic coverage, and treatment types.
This distinction is particularly important for people who need ongoing treatment or prescription management while traveling.
What Should You Compare Before Buying INF HOP?
Before choosing a plan, compare several factors instead of focusing only on the advertised premium.
Medical Maximum
Check the maximum amount available for covered medical expenses and determine whether it is appropriate for your destination.
Deductible
Understand how much you may need to pay before eligible benefits begin.
Pre-Existing Conditions
Read the exact wording governing acute onset and other pre-existing-condition provisions.
Emergency Assistance
Review whether emergency evacuation, repatriation, provider assistance, and other services are included.
Trip Benefits
If travel disruption is a major concern, compare cancellation, interruption, baggage, and delay benefits separately.
Exclusions
Read the exclusions carefully. They can have a major impact on the practical value of the plan.
How INF HOP Fits Into the Broader Insurance Landscape
ZenithNote’s sitemap contains several insurance-related resources covering different types of insurance and claims. For example, readers interested in vehicle-related protection can explore our guide to Amigo auto insurance.
Those resources address different insurance needs, while INF HOP focuses on travel-related protection. Keeping these categories separate is important because coverage requirements vary significantly between auto, travel, health, and other forms of insurance.
Our article about medical costs and insurance coverage also provides useful context for understanding why medical expenses can vary substantially and why insurance terms matter when evaluating potential healthcare costs.
Frequently Asked Questions About INF HOP Insurance
What is INF HOP insurance?
INF HOP is a travel-focused insurance and assistance option intended for eligible international travelers. The exact benefits depend on the selected HOP product and its terms.
Does INF HOP cover medical expenses?
Eligible medical expenses can be covered under applicable HOP plans, subject to the plan’s benefit limits, exclusions, deductible, eligibility rules, and other conditions.
Does INF HOP cover pre-existing conditions?
Some HOP options provide benefits for the acute onset of qualifying pre-existing conditions. This is different from full coverage for ongoing treatment of an existing condition.
Does INF HOP cover emergency evacuation?
Emergency medical evacuation and repatriation assistance can be included in applicable HOP products, subject to the relevant terms and conditions.
Is INF HOP suitable for visitors to the United States?
INF offers visitor-oriented products for eligible non-U.S. residents traveling outside their home country. Travelers should verify the current eligibility requirements before purchasing.
Can I file an INF HOP claim online?
INF provides claims-related services for eligible members and policyholders. The exact procedure depends on the selected plan and type of claim.
Is INF HOP the same as regular health insurance?
No. Travel insurance and assistance products are designed differently from traditional domestic health insurance. Travelers should select coverage according to their destination, trip duration, health needs, and expected risks.
Final Thoughts
INF HOP can be a useful option for eligible international travelers who want medical and travel assistance during a trip. Depending on the selected product, coverage may address unexpected medical treatment, emergency assistance, evacuation, repatriation, and certain travel-related losses.
The most important step is to understand the exact product before purchasing it. Compare medical limits, deductibles, pre-existing-condition provisions, exclusions, eligibility rules, travel benefits, and claims procedures rather than judging a policy solely by its advertised price.
Travelers should also keep their insurance documentation accessible throughout the trip and follow the required claims and emergency-assistance procedures if an unexpected event occurs.
This article is for general informational purposes only and does not constitute insurance, medical, or financial advice. Coverage, eligibility, exclusions, limits, and plan availability can change. Always review the current policy or plan documents before purchasing coverage.