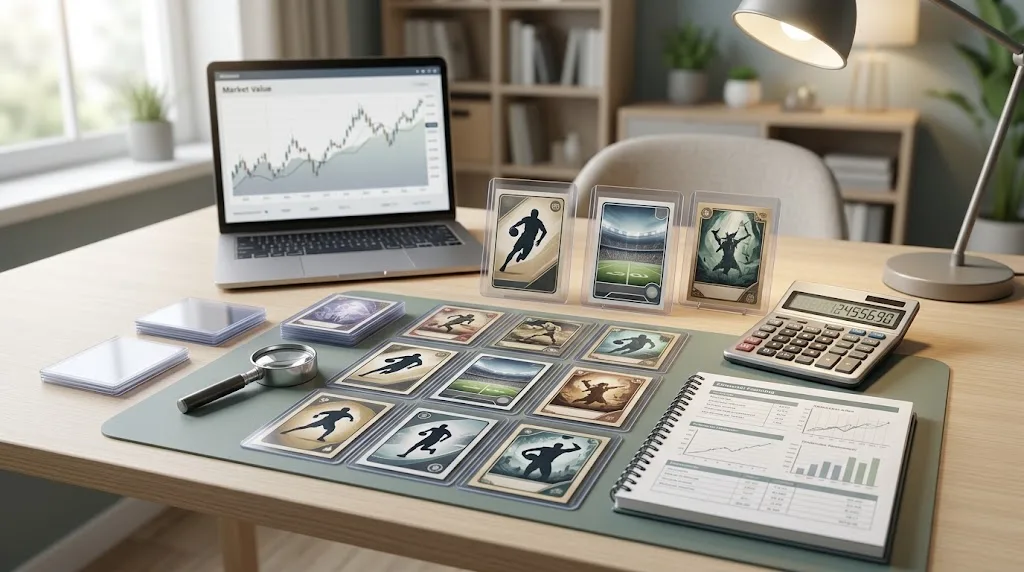
For collectors and investors, this approach can provide an engaging way to think about money. However, collectibles also carry risks, and buying a card should never be treated as a guaranteed investment.
What Does Cardboard Finance Mean?
Cardboard finance combines two worlds that may initially seem unrelated: collectible cards and personal finance.
Trading cards have tangible prices, changing demand, limited availability, condition differences, and active secondary markets. These characteristics make them useful examples for explaining financial concepts without immediately jumping into complicated financial statements or investment models.
For example, a collector who purchases a card for $20 and later discovers that comparable cards sell for $50 has experienced a basic form of price appreciation. But that does not automatically mean the collector earned a $30 profit. Selling fees, shipping, taxes, authentication, grading, and the difficulty of finding a buyer can all affect the actual return.
This simple example demonstrates why understanding the difference between market price and realized return is important.
Why Trading Cards Can Teach Financial Concepts
Collectibles can make financial ideas more tangible because their prices are visible and their markets are often easy for enthusiasts to follow.
A collector can observe how demand changes after a player’s performance, how scarcity affects pricing, how condition influences value, and how sentiment can push prices higher or lower.
The same concepts appear in other markets. Real estate, stocks, commodities, and businesses can all experience changes in supply, demand, sentiment, and perceived value.
ZenithNote’s article on real estate investment opportunities provides another example of how investors evaluate potential returns, market conditions, risk, and long-term value when considering an asset.
Collectibles as an Alternative Asset
Collectibles are sometimes described as alternative assets because their value is not primarily based on traditional financial measures such as corporate earnings or bond interest.
Trading cards can derive value from several factors, including rarity, condition, historical importance, character or player popularity, franchise strength, print run, grading, and collector demand.
However, alternative assets can behave very differently from traditional investments. A collectible may become significantly more valuable during a period of strong demand and then lose value if interest declines.
For this reason, collectors should avoid assuming that historical price growth guarantees future performance.
The Importance of Supply and Demand
Supply and demand are fundamental concepts in economics and finance, and collectible cards provide an easy way to observe them.
If many collectors want a particular card but only a small number of high-quality examples are available, sellers may command higher prices. Conversely, if large numbers of similar cards are available while buyer interest is limited, prices may remain low.
Modern card markets can therefore change quickly when collector sentiment changes.
The same principle applies to other collectible markets. A vintage sports card, for example, may become more desirable because of historical significance, scarcity, player popularity, or renewed interest in the sport.
Using a Vintage Baseball Card as a Finance Example
ZenithNote’s 1979 Topps Pete Rose card guide provides a useful example of how collectors evaluate a physical collectible.
Factors such as authenticity, condition, scarcity, historical significance, and professional grading can influence how collectors perceive the card.
These characteristics illustrate an important financial lesson: an asset’s value is not determined by its physical size or production cost alone. Buyers are willing to pay based on perceived utility, scarcity, demand, history, and confidence in authenticity.
At the same time, a collectible should not automatically be described as a reliable investment. Market prices can fluctuate, and a collector may have difficulty finding a buyer at the price they expect.
Card Condition Can Dramatically Affect Value
Condition is particularly important in the trading-card market.
Two cards featuring the same player or character may have dramatically different values because one has sharp corners, strong centering, a clean surface, and excellent edges while another has creases, whitening, stains, or other damage.
Professional grading services can evaluate cards and assign grades based on their physical condition. Grading can provide greater confidence for buyers, although it also adds costs and does not eliminate market risk.
Collectors should therefore consider grading as one part of a broader evaluation rather than treating a high grade as a guarantee of future appreciation.
Understanding Liquidity in Card Collecting
One of the most important financial concepts that collectibles can teach is liquidity.
Liquidity refers to how easily an asset can be converted into cash without significantly affecting its price.
A publicly traded stock can generally be sold through a market during trading hours. A rare trading card is different. The owner may need to find a suitable buyer, negotiate a price, pay marketplace fees, arrange shipping, or use an auction service.
This means that a card’s estimated market value does not necessarily represent the amount its owner can immediately receive in cash.
Cardboard Finance and Risk Management
Collectibles can also demonstrate why risk management matters.
A collector who spends an excessive portion of their available money on one card becomes highly exposed to changes in that card’s value. If demand declines, the financial impact can be significant.
A more cautious approach is to treat collectible purchases as discretionary spending unless the buyer fully understands the risks and has sufficient financial resources.
Collectors should avoid using emergency savings or money needed for essential expenses to speculate on cards.
Don’t Confuse Collecting With Investing
Collecting and investing can overlap, but they are not identical.
A collector may buy a card because they love the player, character, artwork, history, or nostalgia associated with it. An investor is generally more focused on expected financial return relative to risk.
The same card can therefore serve different purposes for different people.
If you would be happy owning a card even if its market value declined, the purchase may be primarily a collecting decision. If your only reason for purchasing is the expectation that someone else will pay more later, you are taking a more speculative position.
How FOMO Can Affect Collectible Markets
Fear of missing out, commonly called FOMO, can have a powerful influence on collectible markets.
When prices rise rapidly, buyers may assume that the trend will continue indefinitely. They may rush to purchase cards without researching supply, recent sales, condition, or liquidity.
This can create a cycle where rising prices attract more buyers, which pushes prices higher and attracts even more attention.
Eventually, however, demand can cool. When buyers disappear, sellers may discover that the price they expected is no longer achievable.
Taking time to research before purchasing can help reduce emotionally driven decisions.
How to Research a Trading Card Before Buying
Research should come before the purchase rather than after it.
- Identify the exact card: Confirm the year, set, card number, variation, and edition.
- Check authenticity: Be cautious when buying valuable cards from unfamiliar sellers.
- Compare recent sales: Look for actual completed transactions rather than only asking prices.
- Evaluate condition: Examine centering, corners, edges, surface, and other relevant characteristics.
- Consider grading: Determine whether professional authentication or grading makes financial sense.
- Calculate transaction costs: Include marketplace fees, shipping, insurance, grading, and taxes where applicable.
- Consider liquidity: Ask how easily you could resell the card if circumstances changed.
Budgeting for a Collectible Hobby
One of the strongest financial habits a collector can develop is setting a dedicated hobby budget.
Instead of purchasing cards whenever an attractive opportunity appears, establish a monthly or annual amount that can comfortably be spent without interfering with essential expenses.
A hobby budget can make collecting more enjoyable because it creates a clear boundary between entertainment spending and financial obligations.
It also reduces the temptation to justify every collectible purchase as an “investment.”
Cardboard Finance and Diversification
Diversification is another financial concept that collectible markets can help illustrate.
Concentrating money in one player, franchise, card set, or collectible category can create significant exposure to a single market trend.
However, diversification within collectibles does not automatically create a properly diversified investment portfolio. A collection consisting of baseball cards, Pokémon cards, and basketball cards is still concentrated in collectibles.
Traditional financial diversification may involve different asset classes with different risk characteristics. Collectibles can be one discretionary category rather than a replacement for broader financial planning.
The Psychology Behind Collectible Prices
Collectible markets are influenced heavily by psychology.
Nostalgia can cause adults to reconnect with products from childhood. Popular entertainment franchises can generate sudden waves of demand. Sports achievements can increase attention toward a particular player. Social media can amplify trends rapidly.
These emotional factors can influence market prices even when the underlying physical object has not changed.
This makes collectibles a useful example of behavioral finance—the study of how emotions, biases, and human behavior influence financial decisions.
Why Patience Matters
Patience can be valuable in both collecting and personal finance.
Collectors who research before buying may avoid paying inflated prices during periods of excitement. Similarly, waiting can provide time to compare sellers, evaluate condition, and determine whether a purchase actually fits the budget.
Not every opportunity needs an immediate response.
A disciplined buyer can allow enthusiasm to settle before deciding whether a collectible still appears attractive at its current price.
Common Mistakes in Card Collecting
Several mistakes can turn an enjoyable hobby into an unnecessarily expensive one.
- Buying solely because prices are rising
- Confusing asking prices with completed sales
- Ignoring condition
- Failing to verify authenticity
- Overpaying because of FOMO
- Ignoring marketplace and grading fees
- Spending emergency funds on collectibles
- Assuming every collectible will appreciate
- Concentrating too much money in one card or category
How Cardboard Finance Can Improve Financial Literacy
The biggest value of the cardboard finance concept may not be the cards themselves. It may be the opportunity to make financial education more relatable.
Someone who understands why a rare card becomes more valuable can begin to understand supply and demand. Someone who compares purchase price with selling fees can understand transaction costs. Someone who waits for a better opportunity can practice patience and avoid emotional decision-making.
These lessons can then be applied to broader financial decisions.
For example, the same discipline used to research a collectible can be applied when evaluating a major purchase, financing agreement, or investment opportunity.
Cardboard Finance vs. Traditional Investments
Traditional investments such as stocks and bonds generally have established financial structures, regulatory frameworks, and standardized market information.
Collectibles operate differently. Their values can be more subjective and may depend heavily on collector sentiment, rarity, condition, provenance, and marketplace demand.
That does not make collectibles worthless. It simply means they should be evaluated differently.
A collectible can have financial value while also providing enjoyment, historical significance, or personal meaning. Those non-financial benefits are part of why people collect.
How to Build a More Disciplined Collection
A disciplined collector can create a simple set of rules before making purchases.
- Set a maximum spending limit.
- Define the types of cards you want to collect.
- Research recent transaction prices.
- Prioritize authenticity and condition.
- Keep records of purchase prices.
- Track grading and transaction costs.
- Store cards properly.
- Review the collection periodically.
- Avoid buying solely because prices are rising.
Keeping purchase records is especially useful because it provides a more realistic picture of the collection’s financial performance.
Is Cardboard Finance a Real Investment Strategy?
Cardboard finance is better understood as an educational concept and collecting philosophy than as a formal investment strategy.
Some collectibles can appreciate significantly, but future returns are uncertain. Markets can change, buyer preferences can shift, and an item that is popular today may become less desirable later.
Anyone considering collectibles for financial purposes should therefore treat them as higher-risk, less-liquid assets rather than assuming they function like traditional investments.
The strongest use of the cardboard finance concept is arguably educational: it can help people understand valuation, risk, supply and demand, liquidity, behavioral finance, and disciplined spending in a familiar and engaging way.
Frequently Asked Questions
What is cardboard finance?
Cardboard finance is an informal concept that uses collectible trading cards to explore personal finance and investing ideas such as budgeting, valuation, risk, market demand, and long-term financial habits.
Is cardboard finance a type of loan?
No. Cardboard finance is not a conventional loan or financial product. The phrase is generally used to describe the connection between collectible-card culture and financial education.
Can trading cards be investments?
Some trading cards can increase in market value, but appreciation is not guaranteed. Collectibles can be volatile and relatively illiquid, so buyers should understand the risks before treating cards as financial assets.
What makes a trading card valuable?
Factors can include rarity, condition, authenticity, historical significance, player or character popularity, demand, scarcity, edition, and professional grading.
Should beginners invest in trading cards?
Beginners should first learn how the market works and establish a reasonable hobby budget. Collectibles should generally not replace emergency savings or essential financial planning.
Why is card condition important?
Condition can substantially affect collector demand and resale value. Centering, corners, edges, surface quality, and authenticity can all influence how a card is valued.
Final Thoughts
Cardboard finance offers an interesting way to connect the familiar world of collectibles with important financial concepts. Trading cards provide practical examples of supply and demand, valuation, liquidity, risk, market psychology, and the difference between an asking price and a realized return.
The most important lesson is that collecting should be approached with discipline. A card can be enjoyable to own and may potentially appreciate, but neither enjoyment nor past performance guarantees future financial gain.
Set a budget, research purchases carefully, understand condition and authenticity, account for transaction costs, and avoid making decisions based on FOMO. Used this way, the world of collectible cards can become more than a hobby—it can provide an engaging introduction to smarter financial thinking.